BBungah

Sound Asset Lodging

Bitcoin on a hotel balance sheet, without starving the hotel.

A cited guide for hotel owners and investors weighing a Bitcoin reserve: treasury, capital stack and operations. Start with the two calculators below; the full doctrine, sources and memo studio follow.

Decision support and education only — not financial, tax, legal, lending or real-estate advice; you decide. Inspired by CRE × Bitcoin education associated with Chris Drzyzga / TFTC CRE guide. No affiliation claimed.

Two calculators

Sleeve carry check

See what the BTC sleeve costs in coverage before it earns anything. Enter your own figures; nothing is pre-filled and nothing is saved.

Enter NOI, total loan, loan dollars to BTC and coupon to see results.

Formulas: debt yield = NOI ÷ total loan (BTC dollars count, BTC value does not) · DSCR interest-only = NOI ÷ (loan × coupon) · DSCR amortizing = NOI ÷ (loan × mortgage constant, monthly pay) · yearly sleeve cost = BTC dollars × coupon · breakeven growth g solves share × ((1 + g)^years − 1) = coupon × years (ignores fees, taxes and time value).

Debt yield: 10% is the floor; at or below 9% is flagged. DSCR is shown as a value. Reference only: a hotel CMBS broker lists minimum DSCR of about 1.35x–1.40x by segment (PeerSense, Jul 2026). Your lender's terms govern.

Ground rent coverage

Escalate the rent 30 years against your NOI, flat or growing, and a 20% NOI cut.

Enter NOI, year-1 rent and escalator to see results.

Formulas: rent in year t = year-1 rent × (1 + escalator)^(t − 1) · NOI in year t = NOI × (1 + growth)^(t − 1) · coverage = NOI ÷ rent. CPI or fair-market resets are not modeled. Coverage before debt service; your lender sizes on NOI after ground rent.

The context for each calculator is below: financing a BTC sleeve and land / hotel split.

Field notes

Worked examples: the framework applied to a real, recent hotel trade. Thought experiments for decision support, not anyone's plan and not predictions.

Worked example 1 · The Turndown Report · Oct 31, 2026

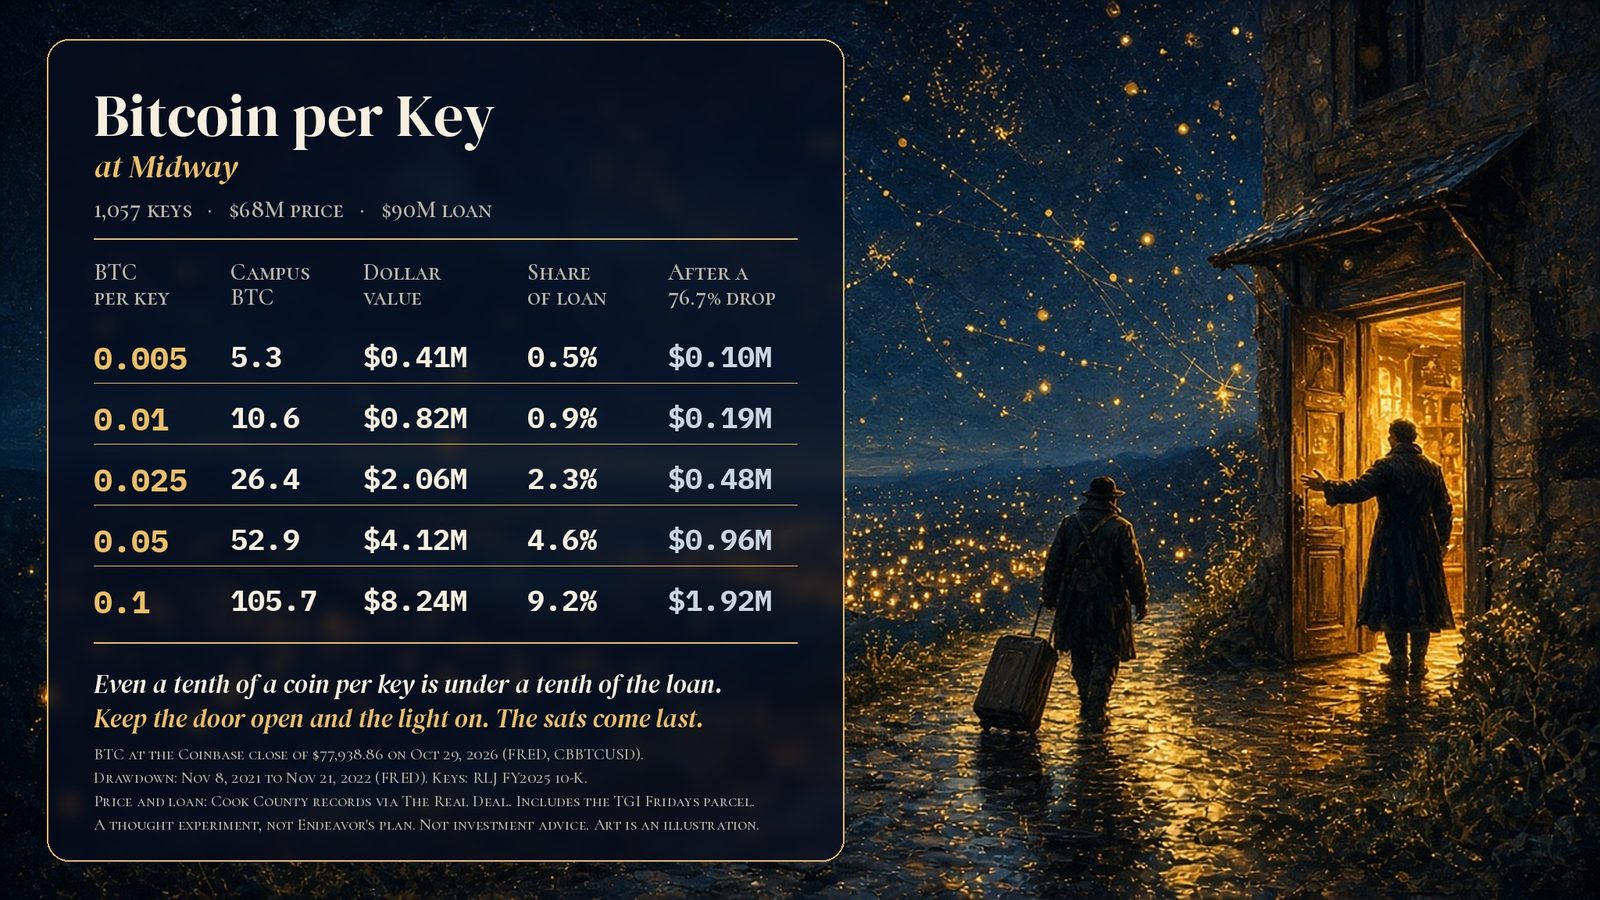
Feed the PIP First: What a Bitcoin per key could look like at Midway (Not a prediction)

Endeavor Hotels bought RLJ's seven-hotel, 1,057-key Midway campus for $68M, about $64,300 a key, with a $90M loan.

The piece walks through what a Bitcoin reserve measured as Bitcoin per key would mean, and why the guest, the PIP and debt service come first.

Bitcoin per key at Midway: 1,057 keys, $68M price, $90M loan. BTC at the Oct 29, 2026 Coinbase close of $77,938.86 via FRED.
BTC per keyCampus BTCDollar valueShare of loanAfter a 76.7% drop
0.0055.3$0.41M0.5%$0.10M
0.0110.6$0.82M0.9%$0.19M
0.02526.4$2.06M2.3%$0.48M
0.0552.9$4.12M4.6%$0.96M
0.1105.7$8.24M9.2%$1.92M

BTC at the Oct 29, 2026 Coinbase close via FRED. Thought experiment, not Endeavor's plan.

The doctrine

Bitcoin treasury, capital stack, and operations for hotel investors — hotel-native and educational. Balance-sheet appreciation as a fifth return driver beside NOI, CapEx quality, leverage, and cap rates.

Why the hotel playbook is breaking

Nightly yield, PIP clocks, fee stacks, labor, group books, debt walls, and brand politics underspecify when you only borrow office/industrial framing. Sound Asset Lodging reweights treasury · capital · operations around STR · Occupancy · ADR · RevPAR, Bitcoin per key, and runway through maturity gaps — leverage-first → balance-sheet-first.

Fifth return driver

Classic hotel returns: grow NOI · improve the asset · manage leverage · favorable cap rates. Fifth — balance-sheet appreciation: a strategic Bitcoin reserve that can compound independently of RevPAR, local property values, and refinancing conditions. Track Bitcoin per key and months of debt service / PIP runway covered by strategic BTC as KPIs — never starve PIP or debt service to fund the reserve.

Three pillars

01

Treasury

After franchise and management fees, free cash flow is the allocation base. Short USD for ops; intermediate liquid reserves; long strategic spot BTC for purchasing power — sized to seasonality and group-book risk, not smooth leases.

  • RevPAR-shock survival months before Tranche 3 sizing
  • Seasonal + group-aware DCA (not NNN-style smooth DCA)
  • Policy and conviction bands before emotion
02

Capital stack

Debt-wall and maturity clocks dominate hotel risk. Strategic reserves and creative collateral are framed as education — runway through refi gaps, not leverage-first speculation.

  • Bitcoin per key as signature KPI
  • Months of debt service covered by strategic BTC
  • Dual-collateral / refi→sats as category education only
03

Operations

PIP and FF&E cycles, labor intensity, and owner–brand–manager politics are hotel deltas vs generic CRE. Payments and loyalty rails come after CapEx realism — mining only where mechanical and brand policy allow.

  • PIP countdown + sats-funded CapEx runway
  • Labor stress scenarios (housekeeping, F&B, desk)
  • Role-based talking points: Owner · Brand · GM

Financing a BTC sleeve

For owners weighing loan-funded Bitcoin on a refinance, a new build or an acquisition. The hotel has to carry the whole loan on its own NOI.

Run the numbers in the sleeve carry check above. Consult a lawyer and a CPA before structuring a sleeve.

Signature metrics

Bitcoin per key
Months of debt service covered by strategic BTC
PIP runway funded (USD + sats equivalent)
RevPAR-shock survival months
% FCF → intermediate vs strategic after fees
Loyalty / payment signal status
Debt yield excluding BTC
Ground rent coverage

Hotel structuring signals

From hospitality-sector dialogue with operators (e.g. Justin Esner on The Real Estate Standard Ep.11): flags often lag 18–24 months; land vs operating/building sleeves can create distinct collateral and optionality; Bitcoin on the owner balance sheet is framed as the emerging normal for competitive owners. Major brand loyalty and payment rails usually gate guest BTC UX — stronger path for independent / soft-brand / owner-led assets.

Separate land vs ops / building for capital-stack optionality
Allocate surplus to spot BTC / digital credit only after fees + PIP + debt service
Brand-policy gate before guest payments or loyalty experiments
First-mover framing around stress / special-servicing windows — thesis, not forecast

Land / hotel split

For fee-simple owners and owners already on a ground lease: the same coverage test applies to the rent you would pay or pay today.

Run the numbers in the ground rent coverage calculator above. Consult a lawyer and a CPA before splitting land from the hotel.

Before you sign

Six questions on keys, locks, upside share and liquidity.

  1. 1Who holds the keys, where, and can the BTC be re-lent?
  2. 2How long is the BTC locked, including after early repayment?
  3. 3What share of the BTC gain do you keep, and from which year?
  4. 4What happens to the BTC if you prepay, default, or BTC falls?
  5. 5Who is the lender affiliated with?
  6. 6How many months of debt service and PIP will you hold in USD, outside the BTC?

What not to do

  • —Never starve PIP or debt service to accumulate BTC.
  • —Never size a hotel loan on the BTC.
  • —Never buy BTC with construction draws.
  • —Never balance coverage on staffing.
  • —Do not ignore flag / brand policy on payments UX or mechanical experiments.
  • —Do not lead with mine-to-heat before treasury discipline and CapEx realism.
  • —Do not treat MSA averages as scarce submarket truth — ask which product class.

Stack memo studio

A memo built from checked market data: demand, capital, operations and supply, each figure row linked to its original source. Markets without a full checked read show their cited snapshot and signals.

Recent Stack memos

Sound Asset Lodging — Las Vegas–Henderson–Paradise MSA

Las Vegas–Henderson–Paradise MSA · 10/20/2026, 11:31:00 AM ET
SourceChecked market read · linked original sources

Sound Asset Lodging — Stack memo · Las Vegas–Henderson–Paradise MSA

Memo date: 2026-10-20 ET · Hold window: 5 years (to 2031-10-20) · Memo type: acquisition / hold

Every figure row opens its original source.

Market thesis (demand)

Demand caution: Conventions are holding while leisure softens; underwrite each segment on its own.

Airlift

Citywides in the next 90 days (to 2027-01-18)

  • 2026-10-18 → 2026-10-21 · Money20/20 USA · attendance: no public read · Money20/20 ↗
  • 2026-10-26 → 2026-10-30 · SupplySide Global (Mandalay Bay) · attendance: no public read · SupplySide Global ↗
  • 2026-11-03 → 2026-11-06 · SEMA Show · attendance: no public read · SEMA ↗
  • 2026-11-15 → 2026-11-18 · HLTH (Venetian Expo) · attendance: no public read · HLTH ↗
  • 2026-11-16 → 2026-11-19 · RE+ (Las Vegas Convention Center) · attendance: no public read · RE+ ↗
  • 2026-11-16 → 2026-11-19 · ISSA Show North America (Mandalay Bay) · attendance: no public read · ISSA ↗
  • 2026-11-21 → 2026-11-21 · Las Vegas Grand Prix race weekend (post-race show Saturday Nov 21) · attendance: no public read · Las Vegas Grand Prix ↗
  • 2026-11-30 → 2026-12-04 · AWS re:Invent · attendance: no public read · AWS re:Invent ↗
  • 2026-12-01 → 2026-12-04 · MJBizCon (Las Vegas Convention Center) · attendance: no public read · MJBizCon ↗
  • 2027 citywide change: the NACS Show moves to Atlanta (Oct 5–8, 2027), an October 2027 gap for Las Vegas · NACS ↗

Visitation and anchors

  • Visitors 2025: 38,545,700; convention delegates 5,988,200 (YE 2025) · LVCVA ↗
  • 2025 hotels: occupancy 80.3% (weekend 88.8%, midweek 76.6%; Strip 83.2%, Downtown 67.5%); average nightly rate $184 (YE 2025) · LVCVA ↗
  • Latest month (Aug 2026): visitors about 3.03M (−4.3%); occupancy 74.1% (−3.4 pts); ADR about $150 (−7.4%); convention attendance 622,700 (+6%) · News 3 Las Vegas ↗
  • Drive market: I-15 at the Nevada–California border averages 43,301 vehicles a day (2025) · LVCVA ↗
  • Economic impact is not demand, and an MSA average is not a submarket.

Capital

Refinance test (not a quote or appraisal; rates as of 2026-10-19): debt is sized on a normalized T12 at current rates. This test outranks every other block in the memo.
  • 10-year Treasury 5.10% (2026-11-12, FRED DGS10) · fred.stlouisfed.org ↗
  • SOFR 3.94% (2026-10-29, FRED) · fred.stlouisfed.org ↗
  • Fed funds target 3.75–4.00% (since the 2026-09-16 FOMC) · federalreserve.gov ↗
  • National lodging CMBS delinquency 6.18% (Sep 2026) · Trepp ↗ national
  • National lodging CMBS special servicing 8.95% (Sep 2026; 8.74% in Aug; 9.91% a year earlier; published 2026-10-13) — national, not Las Vegas–Henderson–Paradise MSA · Trepp ↗ national
Capital caution: A few big casino loans make the national hotel-loan numbers look healthier than a typical hotel.

Deal comps (most recent 1)

  • Embassy Suites Las Vegas (220 keys, near UNLV, about five minutes from the Strip) · closed 2026-09-25 · ~$43.5M cash (Ashford seller) · ~$198K per key (our arithmetic) · cap rate not disclosed · SEC EDGAR ↗ · Hotel Realtor ↗
  • No market-average cap rate: each disclosed cap is read on its own, and an undisclosed cap is never inferred.

Loan watch

  • Four Las Vegas casino resort CMBS loans: $12.01B, 13.0% of the $92.18B securitized lodging market, all current with debt yields of 13.38%–27.90%; without them the nonperforming rate is 6.87% instead of 5.98% (2026-10-06) · Yahoo Finance ↗
  • Named non-casino Las Vegas hotel loans in special servicing or foreclosure: no public read
  • Distressed or receivership assets stay watch, never buy, until debt yield, PIP, insurance and talent all clear.

Hotel-tax collections (latest)

  • Las Vegas LVCVA room tax, by hotel-activity month — Jun 2026: $24.33M (−1.11% YoY, published) · LVCVA share, activity month · LVCVA ↗ tax receipts are not refinance capacity

Operations

Operations caution: Casino owners run most big hotels in-house; supervisors, engineers and F&B leaders are the scarce hires.

Wage floor (steps inside the hold, to 2031-10-20)

  • Labor is costed at the floor in force on each hold date, with no staff cuts, no reduced service and no automating guest-facing roles. If labor breaks the refinance test, the options are revenue, pricing, mix or capital structure.

Contract risk in the hold

  • None public at market level; check each asset's union contract status in diligence
  • A live strike or open contract stays watch until a ratified source says otherwise.

Operator bench

  • Named third-party operator moves in Las Vegas: no public read
  • Operator and GM names come from public announcements; they are not contact suggestions.

Pre-open and transition

  • Hard Rock Las Vegas (late 2027): named pre-open leadership: no public read

Gaps

  • Nevada and Clark County wage-floor steps: no public read
  • Property-level union contract status: no public read

Supply

Supply pressure 4/5 (no ground-up without a hard barrier). Supply caution: Hard Rock's return adds Strip rooms into soft demand, and Downtown is already soft.
  • Inventory 2025: 150,300 hotel rooms (YE 2025) · LVCVA ↗
  • Weighted room inventory Jul 2026: 150,608 (+0.8%) · FOX5 Las Vegas ↗
  • Supply never overrides the refinance test, and low supply is never read as a buy.

Named deliveries inside the hold

  • Hard Rock Las Vegas (former Mirage) · ~3,600 keys (Guitar Hotel 675) · under construction · Strip · late second half of 2027 · Las Vegas Review-Journal ↗
  • AC Hotel + Residence Inn (Mortenson) · 397 keys · broke ground 2026-06-15 · next to the convention center · completion Summer 2028 · Mortenson ↗ · Las Vegas Review-Journal ↗
  • Heart-shaped resort, former SkyVue site (south Strip) · room count: no public read · zoning approved 2026-07-22, entitlement only · timing: no public read · FOX5 Las Vegas ↗
  • Dream Las Vegas · 527 keys · stalled at about 20% complete; McCarthy bought the site · timing: no public read · ENR ↗

Three pillars checklist

  • Capital: the refinance test clears on a normalized T12 at current rates before anything else is sized.
  • Operations: labor at the scheduled floors and contract rates, full staffing, PIP and FF&E funded.
  • Treasury: only free cash flow after fees, debt service and PIP escrow is eligible for a reserve.

Bitcoin tranche (education only)

  • A strategic Bitcoin tranche never fixes a debt-yield or DSCR shortfall; it is sized only after the refinance test clears.
  • Track Bitcoin per key and months of debt service covered as KPIs; never starve PIP or debt service to fund it.
  • Bonuses or tips paid in sats are a concept only: pay and tip rules vary by state and need legal review before any use.

Cardone model, hotel version

Grant Cardone's Cardone Capital multifamily funds are the apartment precedent for pairing property with Bitcoin. This section credits that precedent and sets the hotel rules; it is education, not a recommendation.

Apartment precedent

  • 10X Space Coast fund (300 units, Melbourne FL): $15.0M of Bitcoin bought at closing with investor equity, about 17% of an $88.35M raise (our arithmetic; filing dated 2026-08-24) · SEC EDGAR ↗
  • After closing, monthly property cash flow buys more Bitcoin until the real estate / Bitcoin mix moves from 85/15 to 70/30, over about 4 years (2025-01-22) · coindesk.com ↗ self-reported
  • Boca Raton fund (366 units): $108.0M of Bitcoin at launch, also investor equity, beside $140.0M of filed financing (filing dated 2026-08-24) · SEC EDGAR ↗
  • Stated firm-wide band: Bitcoin at 15–50% of the mix, adjusted for capex, liquidity and debt-maturity needs (page undated) · cardonecapital.com ↗ self-reported

Hotel version rules

  • Bitcoin is bought only from cash left after the PIP, the FF&E reserve, management and franchise fees, and a fully staffed hotel. The FF&E reserve level is a house assumption set by the franchise, management or loan documents, not a sourced figure.
  • Under a lender lockbox or cash sweep, only released cash or new equity can buy Bitcoin; swept cash never does (CMBS loan-structure background) · hklaw.com ↗
  • The refinance test runs on hotel income alone, with no Bitcoin credit. A Bitcoin tranche never fixes a debt-yield shortfall.
  • Bitcoin is never counted on to cover capex or debt maturities: the franchisor sets PIP timing, and a PIP can come due in a Bitcoin drawdown (house rule).
  • Illustration: Boca's debt yield is about 7.5% (166-day NOI of $4.80M annualised ≈ $10.5M ÷ the $140M filed loan; our arithmetic), before any Bitcoin is counted · SEC EDGAR ↗ watch
  • No staff cuts and no automating guest-facing roles to free cash for Bitcoin.

This market, beside any allocation

  • Supply pressure 4/5 (no ground-up without a hard barrier); named projects opening inside the hold: 4 (opening date public for 2); largest below, dated first.
  • Hard Rock Las Vegas (former Mirage) · ~3,600 keys (Guitar Hotel 675) · under construction · Strip · late second half of 2027 · Las Vegas Review-Journal ↗
  • AC Hotel + Residence Inn (Mortenson) · 397 keys · broke ground 2026-06-15 · next to the convention center · completion Summer 2028 · Mortenson ↗ · Las Vegas Review-Journal ↗
  • Dream Las Vegas · 527 keys · stalled at about 20% complete; McCarthy bought the site · timing: no public read · ENR ↗
Size off normalized income net of new supply.
  • Sizing base (this market's normalized T12 income): no checked read, so no allocation is sized here.

Next steps

  1. Run the refinance test on a normalized T12 before any price or tranche discussion.
  2. Diligence the watch items above and the open contract risk before treating any asset as available.
  3. Cost labor at each scheduled floor through the hold; no staff cuts to make the numbers work.
  4. Check named deliveries and the submarket before relying on market-level occupancy or rate.
  5. A person decides: no automatic CapEx, outreach, refinance or Bitcoin purchase comes from this memo.

Sound Asset Lodging · Bungah Capital Intel · Decision support and education only — not financial, tax, legal, lending or real-estate advice. Rows tagged secondary are broker or aggregator reads.

Sound Asset Lodging — Orlando–Kissimmee–Sanford MSA

Orlando–Kissimmee–Sanford MSA · 10/20/2026, 11:30:00 AM ET
SourceChecked market read · linked original sources

Sound Asset Lodging — Stack memo · Orlando–Kissimmee–Sanford MSA

Memo date: 2026-10-20 ET · Hold window: 5 years (to 2031-10-20) · Memo type: acquisition / hold

Every figure row opens its original source.

Market thesis (demand)

Demand caution: Record visitors are not room scarcity; ask about a specific part of Orlando before reading the average.

Airlift

Citywides in the next 90 days (to 2027-01-18)

  • 2026-10-24 → 2026-10-27 · IACP 2026 annual conference (International Association of Chiefs of Police), Orlando · attendance: no public read · IACP ↗
  • November to mid-December convention-center calendar: no public read (the official calendar could not be pulled) no public read
  • 2027 citywide pace / gains-losses: no public read

Visitation and anchors

  • Visitors 2025: 76.7M (70.3M domestic, 6.3M international) (YE 2025) · Visit Orlando ↗ · PR Newswire ↗
  • Orange County Convention Center 2025: 187 events, 2,047,768 attendees (YE 2025) · Visit Orlando ↗
  • Latest month (Aug 2026, Orange County hotels): occupancy 62.4% (−5.8%), ADR $174.95 (−3.2%) (released 2026-10-06) · Orange County Comptroller ↗
  • Economic impact is not demand, and an MSA average is not a submarket.

Capital

Refinance test (not a quote or appraisal; rates as of 2026-10-19): debt is sized on a normalized T12 at current rates. This test outranks every other block in the memo.
  • 10-year Treasury 5.10% (2026-11-12, FRED DGS10) · fred.stlouisfed.org ↗
  • SOFR 3.94% (2026-10-29, FRED) · fred.stlouisfed.org ↗
  • Fed funds target 3.75–4.00% (since the 2026-09-16 FOMC) · federalreserve.gov ↗
  • National lodging CMBS delinquency 6.18% (Sep 2026) · Trepp ↗ national
  • National lodging CMBS special servicing 8.95% (Sep 2026; 8.74% in Aug; 9.91% a year earlier; published 2026-10-13) — national, not Orlando–Kissimmee–Sanford MSA · Trepp ↗ national
Capital caution: Grande Lakes prices a group-resort campus, not the Orlando average.

Deal comps (most recent 1)

  • Grande Lakes Orlando (JW Marriott 1,010 + Ritz-Carlton 582 = 1,592 keys) · closed 2026-09-01 · ~$1.38B (Ryman, equity-funded) · ~$867K per key (our arithmetic) · cap rate not disclosed · SEC EDGAR ↗ · SEC EDGAR ↗
  • No market-average cap rate: each disclosed cap is read on its own, and an undisclosed cap is never inferred.

Loan watch

  • Named Orlando hotel loans in special servicing or foreclosure: no public read
  • Distressed or receivership assets stay watch, never buy, until debt yield, PIP, insurance and talent all clear.

Hotel-tax collections (latest)

  • Orlando (Orange County) Tourist Development Tax, monthly collections — Aug 2026: $24.83M (−3.2% YoY) · collections received · Orange County Comptroller ↗ tax receipts are not refinance capacity

Operations

Operations caution: Disney sets the wage floor here, not Florida's minimum.

Wage floor (steps inside the hold, to 2031-10-20)

  • Florida minimum wage: $15.00/hr; tipped cash $11.98; $15.00 is the last scheduled step; annual inflation increases start 2027-09-30 (eff. 2026-09-30) · National Law Review ↗
  • Labor is costed at the floor in force on each hold date, with no staff cuts, no reduced service and no automating guest-facing roles. If labor breaks the refinance test, the options are revenue, pricing, mix or capital structure.

Contract risk in the hold

  • Disney's union contract (Service Trades Council) runs to Oct 2, 2027, inside the hold; Orlando hotel union pay is compared against Disney scale · UNITE HERE Local 737 ↗ · UNITE HERE ↗ watch
  • Disney union scale: housekeepers reach $24/hr and the current-worker minimum $20.50 at the final scheduled step (Oct 2026); contract expires 2027-10-02 · UNITE HERE ↗ · UNITE HERE Local 737 ↗ watch
  • Hilton Buena Vista Palace (UNITE HERE Local 737): housekeepers $16 → $21/hr at ratification, $24 by June 2028 (2025) · Orlando Weekly ↗
  • A live strike or open contract stays watch until a ratified source says otherwise.

Operator bench

  • Grande Lakes Orlando: Ryman's hotel portfolio is managed by Marriott International (company statement) (2026-09-01) · SEC EDGAR ↗
  • Named third-party operator moves in Orlando: no public read
  • Operator and GM names come from public announcements; they are not contact suggestions.

Pre-open and transition

  • Disney's Lakeshore Lodge (opens 2027-07-01): named pre-open leadership: no public read

Gaps

  • Property-level union contract status: no public read
  • Construction-labor supply for the metro: no public read

Supply

Supply pressure 3/5 (mixed — underwrite by submarket). Supply caution: Orlando covers several distinct hotel areas; ask about a specific one: a meeting-campus resort and an I-Drive box are different supply stories.
  • Inventory 2025: 132,685 hotel rooms; occupancy 71.4%, ADR $202.71, 34.5M room nights (YE 2025) · Visit Orlando ↗
  • Early-planning pipeline: 54 projects / 5,474 rooms; new project announcements 8 / 1,292 rooms (Q2 2026) · Lodging Econometrics ↗
  • Under construction and starts across the metro: no public read
  • Supply never overrides the refinance test, and low supply is never read as a buy.

Named deliveries inside the hold

  • Disney's Lakeshore Lodge · 967 keys · opens 2027-07-01 · Walt Disney World · Disney Parks Blog ↗
  • InterContinental Orlando (I-Drive) · 700 keys · planned; groundbreaking targeted Q1 2026, start not confirmed · open target 2028 (reported 2025-06-30) · GrowthSpotter ↗
  • Tuscana · 1,291 keys · entitlement only (county approved 2026-09-29) · timing: no public read · GrowthSpotter ↗
  • Fairfield Inn + TownePlace Suites, Floridian Town Center (Apopka) · 137 keys · major plan approved 2026-09-03 · timing: no public read · The Apopka Voice ↗

Three pillars checklist

  • Capital: the refinance test clears on a normalized T12 at current rates before anything else is sized.
  • Operations: labor at the scheduled floors and contract rates, full staffing, PIP and FF&E funded.
  • Treasury: only free cash flow after fees, debt service and PIP escrow is eligible for a reserve.

Bitcoin tranche (education only)

  • A strategic Bitcoin tranche never fixes a debt-yield or DSCR shortfall; it is sized only after the refinance test clears.
  • Track Bitcoin per key and months of debt service covered as KPIs; never starve PIP or debt service to fund it.
  • Bonuses or tips paid in sats are a concept only: pay and tip rules vary by state and need legal review before any use.

Cardone model, hotel version

Grant Cardone's Cardone Capital multifamily funds are the apartment precedent for pairing property with Bitcoin. This section credits that precedent and sets the hotel rules; it is education, not a recommendation.

Apartment precedent

  • 10X Space Coast fund (300 units, Melbourne FL): $15.0M of Bitcoin bought at closing with investor equity, about 17% of an $88.35M raise (our arithmetic; filing dated 2026-08-24) · SEC EDGAR ↗
  • After closing, monthly property cash flow buys more Bitcoin until the real estate / Bitcoin mix moves from 85/15 to 70/30, over about 4 years (2025-01-22) · coindesk.com ↗ self-reported
  • Boca Raton fund (366 units): $108.0M of Bitcoin at launch, also investor equity, beside $140.0M of filed financing (filing dated 2026-08-24) · SEC EDGAR ↗
  • Stated firm-wide band: Bitcoin at 15–50% of the mix, adjusted for capex, liquidity and debt-maturity needs (page undated) · cardonecapital.com ↗ self-reported

Hotel version rules

  • Bitcoin is bought only from cash left after the PIP, the FF&E reserve, management and franchise fees, and a fully staffed hotel. The FF&E reserve level is a house assumption set by the franchise, management or loan documents, not a sourced figure.
  • Under a lender lockbox or cash sweep, only released cash or new equity can buy Bitcoin; swept cash never does (CMBS loan-structure background) · hklaw.com ↗
  • The refinance test runs on hotel income alone, with no Bitcoin credit. A Bitcoin tranche never fixes a debt-yield shortfall.
  • Bitcoin is never counted on to cover capex or debt maturities: the franchisor sets PIP timing, and a PIP can come due in a Bitcoin drawdown (house rule).
  • Illustration: Boca's debt yield is about 7.5% (166-day NOI of $4.80M annualised ≈ $10.5M ÷ the $140M filed loan; our arithmetic), before any Bitcoin is counted · SEC EDGAR ↗ watch
  • No staff cuts and no automating guest-facing roles to free cash for Bitcoin.

This market, beside any allocation

  • Supply pressure 3/5 (mixed — underwrite by submarket); named projects opening inside the hold: 4 (opening date public for 2); largest below, dated first.
  • Disney's Lakeshore Lodge · 967 keys · opens 2027-07-01 · Walt Disney World · Disney Parks Blog ↗
  • InterContinental Orlando (I-Drive) · 700 keys · planned; groundbreaking targeted Q1 2026, start not confirmed · open target 2028 (reported 2025-06-30) · GrowthSpotter ↗
  • Tuscana · 1,291 keys · entitlement only (county approved 2026-09-29) · timing: no public read · GrowthSpotter ↗
  • Sizing base (this market's normalized T12 income): no checked read, so no allocation is sized here.

Next steps

  1. Run the refinance test on a normalized T12 before any price or tranche discussion.
  2. Diligence the watch items above and the open contract risk before treating any asset as available.
  3. Cost labor at each scheduled floor through the hold; no staff cuts to make the numbers work.
  4. Check named deliveries and the submarket before relying on market-level occupancy or rate.
  5. A person decides: no automatic CapEx, outreach, refinance or Bitcoin purchase comes from this memo.

Sound Asset Lodging · Bungah Capital Intel · Decision support and education only — not financial, tax, legal, lending or real-estate advice. Rows tagged secondary are broker or aggregator reads.

Sound Asset Lodging — Chicago–Naperville–Elgin MSA

Chicago–Naperville–Elgin MSA · 10/19/2026, 8:01:00 AM ET
SourceChecked market read · linked original sources

Sound Asset Lodging — Stack memo · Chicago–Naperville–Elgin MSA

Memo date: 2026-10-19 ET · Hold window: 5 years (to 2031-10-19) · Memo type: acquisition / hold

Decision support and education only — not financial, tax, legal, lending or real-estate advice. Every figure row opens its original source.

Market thesis (demand)

Demand caution: 2026 RevPAR came from meetings displaced by the World Cup. Strip it out of 2027.

Airlift

  • ORD July 2026 pax: 8,540,764 (+3.21%) (report dated 2026-09-25) · flychicago.com ↗
  • ORD YTD Jul 2026: 51,331,341 (+6.1%) (2026-09-25) · flychicago.com ↗
  • ORD international: Jul 1,610,207 (+4.29%) = 18.9% of pax; YTD 9,309,569 (+8.19%); customs YTD 3,803,697 (+8.12%) (2026-09-25) · flychicago.com ↗
  • ORD operations: Jul 82,365 (+5.52%); YTD +10.57%; intl air-carrier ops YTD +9.83% (2026-09-25) · flychicago.com ↗
  • Forward seats outrank trailing passengers; route counts are not seats.

Citywides in the next 90 days (to 2027-01-17)

  • 2026-10-18 → 2026-10-21 · PACK EXPO International (McCormick Place) · packexpointernational.com ↗
  • 2026-10-29 → 2026-10-31 · ANCC Magnet & Pathway Conference (McCormick) · attendance: no public read · magnetpathwaycon.nursingworld.org ↗
  • 2026-11-07 → 2026-11-08 · AHA Resuscitation Science Symposium (McCormick) · attendance: no public read · professional.heart.org ↗
  • 2026-11-29 → 2026-12-03 · RSNA 2026 (McCormick); 700+ exhibitors · attendance: no public read · RSNA ↗
  • 2026-12-16 → 2026-12-18 · Midwest Clinic (McCormick); 18,000+ annual attendees · midwestclinic.org ↗
  • 2027-01-07 → 2027-01-10 · ABCA Convention (McCormick) · attendance: no public read · abca.org ↗
  • 2027 pace / losses: no public read (no McCormick/Choose Chicago 2027 pace release found)

Visitation and anchors

  • Visitors 2025: 56.8M (+nearly 1.5M vs 2024) (2026-06-25) · Choose Chicago ↗
  • Not a host, but 2026 carries meetings displaced by the World Cup: normalize T12. normalize T12
  • Economic impact is not demand, and an MSA average is not a submarket.

Capital

Refinance test (not a quote or appraisal; rates as of 2026-10-19): debt is sized on a normalized T12 at current rates. This test outranks every other block in the memo.
  • 10-year Treasury 5.10% (2026-11-12, FRED DGS10) · fred.stlouisfed.org ↗
  • SOFR 3.94% (2026-10-29, FRED) · fred.stlouisfed.org ↗
  • Fed funds target 3.75–4.00% (since the 2026-09-16 FOMC) · federalreserve.gov ↗
  • National lodging CMBS delinquency 6.18% (Sep 2026) · Trepp ↗ national
  • National lodging CMBS special servicing 8.95% (Sep 2026; 8.74% in Aug; 9.91% a year earlier; published 2026-10-13) — national, not Chicago–Naperville–Elgin MSA · Trepp ↗ national
Capital caution: Strike and foreclosure risk come before any tax lift.
Holdability read (as written)
  • Downtown trades at $85–129K/key are basis plays well below replacement cost, with no disclosed caps (TRD 2026-10-08; CRE Direct 2026-05-20). A 2026 T12 carrying World Cup-displaced meetings overstates debt yield. Normalize it before testing debt yield. Labor is underwritten at the Local 1 successor contract with a strike/lost-hours contingency through RSNA week, never offset by FTE cuts. Debt test not yet cleared.

Deal comps (most recent 4)

  • Royal Sonesta River North → Hotel 505 River North (505 N State) · reported 2026-10-08 · $21.0M (−62% vs the $55M 2019 price) · 261 keys · ~$85K · cap not disclosed · The Real Deal ↗
  • La Quinta Inn & Suites Chicago downtown · Jun 2026 · $30.5M · 239 keys · $127,615 · cap not disclosed · Commercial Real Estate Direct ↗
  • Blackstone Hotel, Autograph Collection (636 S Michigan) · May 2026 · $43.2M (−28% vs $59.5M in 2016) · 335 (CRE Direct) / 355 (TRD) keys · $128,955 (CRE Direct) / ~$121K (TRD) · cap not disclosed · Commercial Real Estate Direct ↗ · The Real Deal ↗
  • Homewood Suites downtown Chicago · May 2026 · $29.0M · 233 keys · $124,463 · cap not disclosed · Commercial Real Estate Direct ↗
  • No market-average cap rate: each disclosed cap is read on its own, and an undisclosed cap is never inferred.

Loan watch

  • Palmer House Hilton (1,641 keys; Thor Equities; JPMBB 2015-C32 et al.) · $328.9M (Trepp/CRE Daily); "$332.2M mortgage" (TRD) · In foreclosure since the 2022 default; the hotel foreclosure is held up by litigation over parcel-split disclosure (JPMorgan). The retail/office/garage parcel (17 E Monroe), taken by LNR at a $29.5M 2023 sheriff's sale, went to an online auction with a $1.9M starting bid (Aug 2026). The hotel is also one of 6 Local 1 strike hotels since 2026-10-09, so strike losses fall on lender/recovery NOI (2026-10-01; 2026-07-28) · CRE Daily ↗ · The Real Deal ↗ · Chicago Sun-Times ↗ watch
  • MPEA Expansion Project Bonds (back the McCormick campus, including the Hyatt Regency McCormick (1,258) and Marriott Marquis (1,205)) · Debt service FY26 $228.0M / FY27 $236.6M / FY28 $245.6M · Tax collections are expected to fall short of debt service FY26–FY28, and MPEA intends to refinance portions of the bonds (FY26–28 plan (Apr 2025)) · MPEA ↗
  • Named Chicago hotel loan with a 2026–27 maturity in special servicing or delinquency (besides Palmer House) · no public read (Trepp free PDFs and KBRA BusinessWire checked) (2026-10-11)
  • Distressed or receivership assets stay watch, never buy, until debt yield, PIP, insurance and talent all clear.

Hotel-tax collections (latest)

  • Chicago MPEA hotel tax, monthly collections — Aug 2026: $9.87M (+11.1% YoY) · cash collected (state-remitted) · MPEA ↗ tax receipts are not refinance capacity

Operations

Operations caution: A live strike; underwrite a contingency, never a service cut.

Wage floor (steps inside the hold, to 2031-10-19)

  • Chicago minimum wage (4+ employees): $17.05/hr; tipped cash $12.96 (eff. 2026-07-01) · CBS News ↗ · City of Chicago ↗
  • Labor is costed at the floor in force on each hold date, with no staff cuts, no reduced service and no automating guest-facing roles. If labor breaks the refinance test, the options are revenue, pricing, mix or capital structure.

Contract risk in the hold

  • Local 1 strike at 6 hotels since Oct 9 2026, within a 46-hotel dispute; Marriott Marquis operator contract ends Sep 2027 · unitehere1.org ↗ · Chicago Sun-Times ↗ · nbcchicago.com ↗ watch
  • Local 1 2023 contract (Marriott/Hilton/Hyatt-operated): 3-yr; $25/hr minimum non-tipped; daily room cleaning restored; health preserved; pension strengthened; expiry Aug 31 2026 (2023-08-17) · unitehere1.org ↗
  • Local 1 2026 strike: Started Oct 9 2026, 6 hotels; demands: wages, health, pension, civil-rights protections, safer workloads; union seeks a 5-yr contract (2026-10-09) · Chicago Sun-Times ↗ watch
  • Strike status: Second day (Oct 10) with no negotiations scheduled; workers to stay out "until an agreement is reached"; Marriott says it remains available to meet; 40 more hotels could be struck without notice (2026-10-11) · nbcchicago.com ↗ · nonrevtravelnews.com ↗ watch
  • A live strike or open contract stays watch until a ratified source says otherwise.

Operator bench

  • Davidson Hospitality Group / Pivot: Hotel Lincoln, JdV (182) for Jordache Enterprises; also Hotel Zachary (Tribute), Hyatt Centric Mag Mile, Hyatt Lodge Oak Brook · traveldailynews.com ↗
  • Remington Hospitality: Sofitel Chicago Magnificent Mile (415) — from May 2025, franchise under Braemar master HMA; all staff retained · Hotel Online ↗
  • Marriott (Marquis Chicago, 1,205): MPEA-owned; QMA expires Sep 20 2027; MPEA RFP #2026-15-M seeks national-brand convention operator, key money; MPEA approves GM, DOSM, DOF, DRM; planned full rooms + meeting-space renovation (timing TBD) · govcb.com ↗
  • Latest management change: Marriott Marquis Chicago: operator re-bid (RFP Mar 2026; QMA expiry Sep 2027) — winner no public read. · govcb.com ↗
  • Operator and GM names come from public announcements; they are not contact suggestions.

Pre-open and transition

  • Named pre-open leadership: no public read

Gaps

  • Local 1 settlement terms / strike end date: no public read
  • Whether strike extends into RSNA week: no public read
  • MPEA Marquis operator award: no public read
  • Illinois hotel-specific ordinances (panic button etc.): no public read

Supply

Supply pressure 2/5 (tailwind — but a low score is never a buy signal on its own). Supply caution: Flat supply is not the same as safe; new keys come from conversions, not cranes.
  • UC intensity: CBD net change −0.1% (2026) and +1.5% (2027) · Choose Chicago ↗
  • Submarket concentration: 2027 adds land in the Loop / River North / River West · Choose Chicago ↗
  • Supply never overrides the refinance test, and low supply is never read as a buy.

Named deliveries inside the hold

  • Bally's Chicago Casino + Hotel · 500 keys · UC · River West · Moved to end of Q1/Q2 2027 · Choose Chicago ↗ · stayinthenew.com ↗ secondary
  • Ruby Hotel Chicago (conversion of the Inn of Chicago; IHG franchise) · 412 keys · Renovation from H2 2026 · Streeterville / Mag Mile · 2027 · hotelnewsresource.com ↗
  • The Monroe Hotel (111 W Monroe; adaptive reuse) · 327 keys · Proposed / in development · Loop · 2027 · primegroupinc.com ↗
  • Burnham Center luxury hotel (111 W Washington; Reschke) · 250–300 keys · Proposed; no operator or timeline · Loop · timing: no public read · Hoodline ↗
  • The Duke of Wells (Unbound Collection by Hyatt) · 203 keys · Coming · Old Town · timing: no public read · stayinthenew.com ↗ secondary
  • The Neighborhood Hotel – West Loop · 76 suites · Coming · Fulton Market · 2027 · stayinthenew.com ↗ secondary

Three pillars checklist

  • Capital: the refinance test clears on a normalized T12 at current rates before anything else is sized.
  • Operations: labor at the scheduled floors and contract rates, full staffing, PIP and FF&E funded.
  • Treasury: only free cash flow after fees, debt service and PIP escrow is eligible for a reserve.

Bitcoin tranche (education only)

  • A strategic Bitcoin tranche never fixes a debt-yield or DSCR shortfall; it is sized only after the refinance test clears.
  • Track Bitcoin per key and months of debt service covered as decision-support KPIs; never starve PIP or debt service to fund it.
  • Bonuses or tips paid in sats are a concept only: pay and tip rules vary by state and need legal review before any use.

Cardone model, hotel version

Grant Cardone's Cardone Capital multifamily funds are the apartment precedent for pairing property with Bitcoin. This section credits that precedent and sets the hotel rules; it is education and decision support, not a recommendation.

Apartment precedent

  • 10X Space Coast fund (300 units, Melbourne FL): $15.0M of Bitcoin bought at closing with investor equity, about 17% of an $88.35M raise (our arithmetic; filing dated 2026-08-24) · SEC EDGAR ↗
  • After closing, monthly property cash flow buys more Bitcoin until the real estate / Bitcoin mix moves from 85/15 to 70/30, over about 4 years (2025-01-22) · coindesk.com ↗ self-reported
  • Boca Raton fund (366 units): $108.0M of Bitcoin at launch, also investor equity, beside $140.0M of filed financing (filing dated 2026-08-24) · SEC EDGAR ↗
  • Stated firm-wide band: Bitcoin at 15–50% of the mix, adjusted for capex, liquidity and debt-maturity needs (page undated) · cardonecapital.com ↗ self-reported

Hotel version rules

  • Bitcoin is bought only from cash left after the PIP, the FF&E reserve, management and franchise fees, and a fully staffed hotel. The FF&E reserve level is a house assumption set by the franchise, management or loan documents, not a sourced figure.
  • Under a lender lockbox or cash sweep, only released cash or new equity can buy Bitcoin; swept cash never does (CMBS loan-structure background) · hklaw.com ↗
  • The refinance test runs on hotel income alone, with no Bitcoin credit. A Bitcoin tranche never fixes a debt yield shortfall.
  • Bitcoin is never counted on to cover capex or debt maturities: the franchisor sets PIP timing, and a PIP can come due in a Bitcoin drawdown (house rule).
  • Illustration: Boca's debt yield is about 7.5% (166-day NOI of $4.80M annualised ≈ $10.5M ÷ the $140M filed loan; our arithmetic), before any Bitcoin is counted · SEC EDGAR ↗ watch
  • No staff cuts and no automating guest-facing roles to free cash for Bitcoin.

This market, beside any allocation

  • Supply pressure 2/5 (tailwind — but a low score is never a buy signal on its own); named projects opening inside the hold: 6 (opening date public for 4); largest below, dated first.
  • Bally's Chicago Casino + Hotel · 500 keys · UC · River West · Moved to end of Q1/Q2 2027 · Choose Chicago ↗ · stayinthenew.com ↗ secondary
  • Ruby Hotel Chicago (conversion of the Inn of Chicago; IHG franchise) · 412 keys · Renovation from H2 2026 · Streeterville / Mag Mile · 2027 · hotelnewsresource.com ↗
  • The Monroe Hotel (111 W Monroe; adaptive reuse) · 327 keys · Proposed / in development · Loop · 2027 · primegroupinc.com ↗
  • Sizing base (this market's normalized T12 income): no checked read, so no allocation is sized here.

Next steps (decision support)

  1. Run the refinance test on a normalized T12 (event windows stripped) before any price or tranche discussion.
  2. Diligence the watch items above (1 loan-watch rows) and the open contract risk before treating any asset as available.
  3. Cost labor at each scheduled floor through the hold; no staff cuts to make the numbers work.
  4. Check named deliveries and the submarket before relying on market-level occupancy or rate.
  5. A person decides: no automatic CapEx, outreach, refinance or Bitcoin purchase comes from this memo.

Sound Asset Lodging · Bungah Capital Intel · decision support · rows tagged secondary are broker or aggregator reads

Sound Asset Lodging — Urban Honolulu MSA / Oahu

Urban Honolulu MSA / Oahu · 10/19/2026, 8:00:00 AM ET
SourceChecked market read · linked original sources

Sound Asset Lodging — Stack memo · Urban Honolulu MSA / Oahu

Memo date: 2026-10-19 ET · Hold window: 5 years (to 2031-10-19) · Memo type: acquisition / hold

Decision support and education only — not financial, tax, legal, lending or real-estate advice. Every figure row opens its original source.

Market thesis (demand)

Demand caution: Japan seats are down, and the convention center is under renovation. Waikīkī isn't Oʻahu.

Airlift

  • Statewide transpacific seats Aug 2026: 1,106,477 (−0.7%); flights 5,038 (+0.7%) (2026-09-30) · State of Hawaii ↗
  • Japan nonstop seats Q4 2026 (HNL only): Oct 98,568 / Nov 103,512 / Dec 107,718 (preliminary) (as of 2026-08-14) · simpleviewinc.com ↗
  • Canada nonstop seats Q4 2026 (statewide): Oct 18,231 / Nov 38,724 / Dec 46,846 (preliminary) (as of 2026-08-14) · simpleviewinc.com ↗
  • Forward seats outrank trailing passengers; route counts are not seats.

Citywides in the next 90 days (to 2027-01-17)

  • 2026-12-10 → 2026-12-13 · Honolulu Marathon Expo (HCC; 60,000 listed) + JAL Honolulu Marathon (Dec 13) · hawaiiconvention.com ↗ · honolulumarathon.org ↗
  • 2026-12-01 → 2027-01-03 · 'Twas the Light Before Christmas on Ice (HCC; 20,000 listed) · hawaiiconvention.com ↗
  • 2027-01-13 → 2027-01-19 · TransPacific Volleyball Championships (HCC; 15,000 listed) · hawaiiconvention.com ↗
  • 2027 citywide gains/losses: no public read (renovation suppresses MCI; no pace release found)

Visitation and anchors

  • Statewide Aug / YTD visitors: 772,039 (−5.6%) / 6,693,107 (+1.8%) (2026-09-30) · State of Hawaii ↗
  • Economic impact is not demand, and an MSA average is not a submarket.

Capital

Refinance test (not a quote or appraisal; rates as of 2026-10-19): debt is sized on a normalized T12 at current rates. This test outranks every other block in the memo.
  • 10-year Treasury 5.10% (2026-11-12, FRED DGS10) · fred.stlouisfed.org ↗
  • SOFR 3.94% (2026-10-29, FRED) · fred.stlouisfed.org ↗
  • Fed funds target 3.75–4.00% (since the 2026-09-16 FOMC) · federalreserve.gov ↗
  • National lodging CMBS delinquency 6.18% (Sep 2026) · Trepp ↗ national
  • National lodging CMBS special servicing 8.95% (Sep 2026; 8.74% in Aug; 9.91% a year earlier; published 2026-10-13) — national, not Urban Honolulu MSA / Oahu · Trepp ↗ national
Capital caution: Tax growth is mostly rate; land and leasehold drive value.
Holdability read (as written)
  • Without an operating-hotel cap print, holdability can't be benchmarked. The visible capital is long-dated: fee and land buyers, plus Park choosing to refinance HHV off CMBS rather than roll it. Underwrite from a T12 at the current tax load: TAT rose to 11% on 2026-01-01, so the guest-facing total is now 18.712%. Test debt yield on a normalized T12, with labor at contract. Debt test not yet cleared.

Deal comps (most recent 4)

  • Royal Hawaiian Hotel land (10.3-acre fee under the hotel; Kyo-ya keeps the hotel on a ground lease to 2076) · closed ~2025-11-06 ("Thursday" before 2025-11-11) · $510M (land only) · n/a (land) · cap not disclosed · staradvertiser.com ↗
  • Oasis Hotel Waikiki, ground under the hotel · Jul 2025 (reported 2025-09-03) · $23M · 96 (hotel) keys · ~$240K (arithmetic, fee only) · cap not disclosed · Business Journals ↗
  • Hyatt Regency Waikiki, leased-fee interest · Aug 2025 · undisclosed · 1,230 (hotel) keys · cap not disclosed · montgomerystreetpartners.com ↗ · akm.ru ↗ secondary
  • Four Seasons Hualālai land (Big Island; context) · Aug 2025 · ~$400M · cap not disclosed · staradvertiser.com ↗
  • No market-average cap rate: each disclosed cap is read on its own, and an undisclosed cap is never inferred.

Loan watch

  • Hilton Hawaiian Village (Park; 2,860± keys), HHV 2016 CMBS · $1.275B · Repaid in full 2026-09-30, ahead of the 2026-11-01 maturity. Funded with $700M Bonnet Creek delayed-draw mortgage + $600M unsecured delayed-draw term loan; the resort is now unencumbered · SEC EDGAR ↗ · nasdaq.com ↗
  • Hyatt Regency Waikiki Beach Resort & Spa (1,230 keys), HONO 2021-LULU · $302.2M · Watch. Special servicing, Oct 2026, after missing its extended final maturity. No debt yield is shown until the cash-flow figures reconcile (2026-10-16) · Commercial Observer ↗ watch
  • Distressed or receivership assets stay watch, never buy, until debt yield, PIP, insurance and talent all clear.

Hotel-tax collections (latest)

  • Honolulu statewide TAT cash collections, monthly — Jun 2026: $69M (+20.28% YoY, includes 10.25%→11% rate step) · cash collected, statewide · rate-driven · State of Hawaii ↗ tax receipts are not refinance capacity

Operations

Operations caution: The Waikīkī standard is the floor, in Tier 1's highest-wage market.

Wage floor (steps inside the hold, to 2031-10-19)

  • Hawaii minimum wage: $16.00/hr; next step $18.00 on 2028-01-01 (eff. 2026-01-01) · State of Hawaii ↗ · State of Hawaii ↗
  • Labor is costed at the floor in force on each hold date, with no staff cuts, no reduced service and no automating guest-facing roles. If labor breaks the refinance test, the options are revenue, pricing, mix or capital structure.

Contract risk in the hold

  • All Local 5 Waikīkī hotels are under new contracts · UNITE HERE Local 5 ↗ · thegardenisland.com ↗ · UNITE HERE Local 5 ↗ watch
  • Local 5 — Hilton Hawaiian Village: 40-day strike (Sep 24 → Nov 4 2024), 1,800+ workers; ratified (2024-11-04) · UNITE HERE Local 5 ↗ watch
  • HHV contract terms: 4-yr; "up to $10 per hour in wage increases over four years" (confirmed on free reprint). Star-Advertiser estimate: avg Local 5 HK ~$28/hr pre-strike → ~$38/hr; front desk ~$31 → ~$41; bartender ~$35 → ~$45 (all-in HK employer cost >$121k/yr). Tipped vs uniformed raise split: no public read (paywalled) (2024-11-06) · thegardenisland.com ↗ · staradvertiser.com ↗ watch
  • Local 5 — Kyo-ya / Marriott (Royal Hawaiian, Sheraton Princess Kaiulani, Sheraton Waikiki, Waikiki Beach Marriott, Moana Surfrider): 2,500+ workers ratified "similar agreements"; wages, job security, workload/staffing commitments (Nov 2024) · UNITE HERE Local 5 ↗
  • A live strike or open contract stays watch until a ratified source says otherwise.

Operator bench

  • Highgate: Major Hawaii operator since 2011 (Courtyard Waikiki); lost Renaissance Honolulu; Romer House Waikiki remains · hawaiihotelhui.com ↗
  • Latest management change: Renaissance Honolulu: Highgate → Crescent (2025). · hawaiihotelhui.com ↗
  • Operator and GM names come from public announcements; they are not contact suggestions.

Pre-open and transition

  • Named pre-open leadership: no public read

Gaps

  • Waikiki Standard hourly scale + expiry dates: no public read
  • Hyatt Regency Waikiki settlement details: no public read
  • Oahu pipeline + pre-open leaders: no public read
  • Hotel GC roster: no public read

Supply

Supply pressure 1/5 (tailwind — but a low score is never a buy signal on its own). Supply caution: Zero cranes is not the same as pricing power; Waikīkī is not the same as Oʻahu.
Low new supply is not low risk. Read this score together with the loan watch above before treating it as a tailwind.
  • UC intensity: 0 rooms · Hawaii Tourism Authority ↗
  • Submarket concentration: Planned keys in Downtown/Kakaʻako and Kapolei, not Waikīkī (except Residence Inn 162) · Hawaii Tourism Authority ↗
  • Supply never overrides the refinance test, and low supply is never read as a buy.

Named deliveries inside the hold

Three pillars checklist

  • Capital: the refinance test clears on a normalized T12 at current rates before anything else is sized.
  • Operations: labor at the scheduled floors and contract rates, full staffing, PIP and FF&E funded.
  • Treasury: only free cash flow after fees, debt service and PIP escrow is eligible for a reserve.

Bitcoin tranche (education only)

  • A strategic Bitcoin tranche never fixes a debt-yield or DSCR shortfall; it is sized only after the refinance test clears.
  • Track Bitcoin per key and months of debt service covered as decision-support KPIs; never starve PIP or debt service to fund it.
  • Bonuses or tips paid in sats are a concept only: pay and tip rules vary by state and need legal review before any use.

Cardone model, hotel version

Grant Cardone's Cardone Capital multifamily funds are the apartment precedent for pairing property with Bitcoin. This section credits that precedent and sets the hotel rules; it is education and decision support, not a recommendation.

Apartment precedent

  • 10X Space Coast fund (300 units, Melbourne FL): $15.0M of Bitcoin bought at closing with investor equity, about 17% of an $88.35M raise (our arithmetic; filing dated 2026-08-24) · SEC EDGAR ↗
  • After closing, monthly property cash flow buys more Bitcoin until the real estate / Bitcoin mix moves from 85/15 to 70/30, over about 4 years (2025-01-22) · coindesk.com ↗ self-reported
  • Boca Raton fund (366 units): $108.0M of Bitcoin at launch, also investor equity, beside $140.0M of filed financing (filing dated 2026-08-24) · SEC EDGAR ↗
  • Stated firm-wide band: Bitcoin at 15–50% of the mix, adjusted for capex, liquidity and debt-maturity needs (page undated) · cardonecapital.com ↗ self-reported

Hotel version rules

  • Bitcoin is bought only from cash left after the PIP, the FF&E reserve, management and franchise fees, and a fully staffed hotel. The FF&E reserve level is a house assumption set by the franchise, management or loan documents, not a sourced figure.
  • Under a lender lockbox or cash sweep, only released cash or new equity can buy Bitcoin; swept cash never does (CMBS loan-structure background) · hklaw.com ↗
  • The refinance test runs on hotel income alone, with no Bitcoin credit. A Bitcoin tranche never fixes a debt yield shortfall.
  • Bitcoin is never counted on to cover capex or debt maturities: the franchisor sets PIP timing, and a PIP can come due in a Bitcoin drawdown (house rule).
  • Illustration: Boca's debt yield is about 7.5% (166-day NOI of $4.80M annualised ≈ $10.5M ÷ the $140M filed loan; our arithmetic), before any Bitcoin is counted · SEC EDGAR ↗ watch
  • No staff cuts and no automating guest-facing roles to free cash for Bitcoin.

This market, beside any allocation

  • Supply pressure 1/5 (tailwind — but a low score is never a buy signal on its own); named projects opening inside the hold: 5 (opening date public for 5); largest below, dated first.
  • 1500 Kapiʻolani Hotel · 444 keys · Final planning · Ala Moana / Kakaʻako · 2028 · Hawaii Tourism Authority ↗
  • Home2 Suites by Hilton Honolulu Downtown · 295 keys · Final planning · Downtown · 2027 · Hawaii Tourism Authority ↗
  • Element by Marriott Oʻahu Kapolei · 207 keys · Final planning · Kapolei · 2028 · Hawaii Tourism Authority ↗
  • Sizing base (this market's normalized T12 income): no checked read, so no allocation is sized here.

Next steps (decision support)

  1. Run the refinance test on a normalized T12 before any price or tranche discussion.
  2. Diligence the watch items above (1 loan-watch rows) and the open contract risk before treating any asset as available.
  3. Cost labor at each scheduled floor through the hold; no staff cuts to make the numbers work.
  4. Check named deliveries and the submarket before relying on market-level occupancy or rate.
  5. A person decides: no automatic CapEx, outreach, refinance or Bitcoin purchase comes from this memo.

Sound Asset Lodging · Bungah Capital Intel · decision support · rows tagged secondary are broker or aggregator reads

Educational synthesis only. Lineage: Chris Drzyzga / TFTC CRE (tftc.io/cre); hotel dialogue via The Real Estate Standard Ep.11 (Justin Esner). Bungah is not affiliated with TFTC, Mr. Drzyzga, or the show.